BIC Tip #1073: Pre-Qualification vs. Pre-Approval
When it comes to helping buyers prepare for the home-buying process, few terms get mixed up more than pre-qualification and pre-approval. As brokers, it’s our job to make sure clients — and sometimes even agents — understand the difference.
Let’s break it down Notorious BIC style.
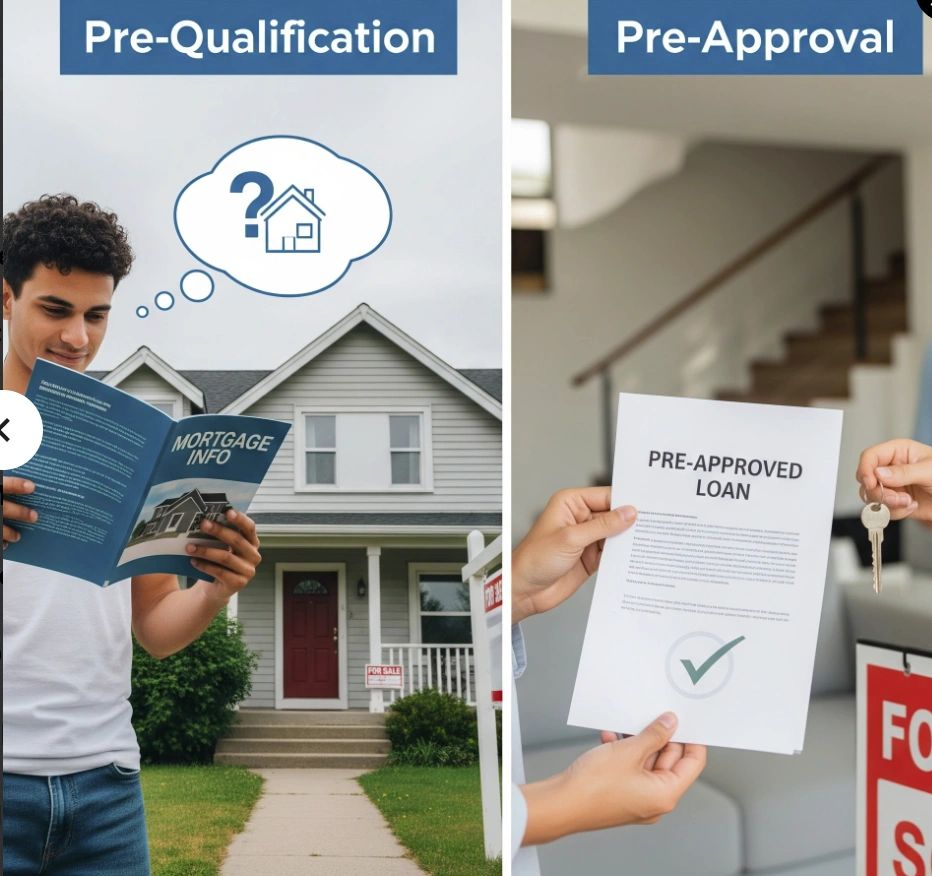
💬 What Is Pre-Qualification?
Pre-qualification is a conversation. It’s typically based on what a buyer tells the lender — income, debts, and assets — without any verification.
It’s fast, easy, and a good starting point to get a general sense of what a buyer might afford.
But here’s the catch: it’s only as accurate as the information provided. There’s no credit pull or documentation review. In other words — it’s an estimate, not a promise.
🏦 What Is Pre-Approval?
Pre-approval goes a step further — it’s verification.
The lender reviews the buyer’s financial documents, credit report, employment, and debt-to-income ratio. When a buyer gets pre-approved, the lender issues a formal letter stating they’re conditionally approved for a certain amount.
That means the buyer has real buying power. In a competitive market, this can be the difference between winning and losing a home.
⚖️ Why It Matters for Brokers
As the Broker-in-Charge, you set the tone for professionalism and accuracy in your firm. Make sure your agents are:
✅ Explaining both terms clearly to clients
✅ Encouraging pre-approval before house hunting
✅ Recognizing that sellers take pre-approved buyers more seriously
Remember — a pre-qualified buyer is interested.
A pre-approved buyer is ready.
💡 The Notorious Takeaway
Don’t let your clients confuse potential with proof.
Pre-qualification starts the conversation, but pre-approval seals the deal.
Educate your agents, guide your buyers, and make sure your firm operates with clarity and confidence.
📚 Stay educated. Stay compliant. Stay Notorious.
#NotoriousBIC #BicTips #RealEstateEducation #MortgageTips #HomeBuying #BrokerInCharge #PreApproval #PreQualification #RealEstateTraining